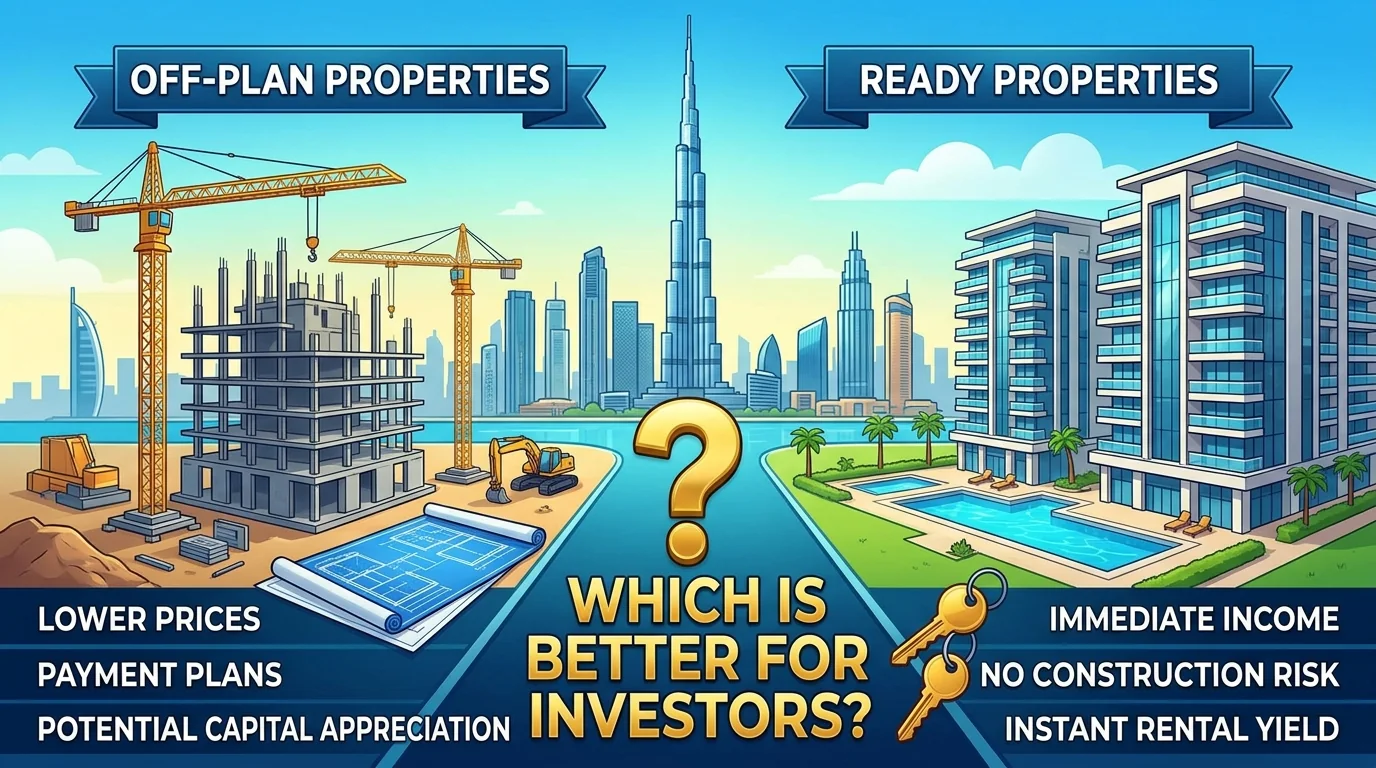
Choosing between off-plan property in Dubai and ready property comes down to your investment goals, risk appetite and cash-flow strategy. Here's how they compare.
1. Affordability and pricing
Off-plan: typically 10% to 30% cheaper than comparable ready property, so you enter the market at a lower price.
Ready: priced at market rates, generally higher because it's available immediately.
2. Payment flexibility
Off-plan: attractive instalment plans, such as 1% a month, post-handover plans or 60/40 splits, reduce the cash you need upfront.
Ready: requires full payment on purchase, in cash or with a mortgage.
3. ROI and capital appreciation
Off-plan: strong potential for capital gains as projects near completion, especially in emerging areas.
Ready: steady returns, mostly through rental income, with less upside from capital growth.
4. Risk
Off-plan: higher risk from construction delays, developer issues and market shifts, so due diligence on the developer is essential. Your payments are protected in a RERA-regulated escrow account.
Ready: lower risk, because you can inspect the property and take possession immediately.
5. Rental income and liquidity
Off-plan: no rental income until handover, so returns come later but can be substantial.
Ready: immediate rental income, with typical yields of 5% to 9% depending on location.
6. Customisation
Off-plan: buying early gives you the best choice of layouts, views and sometimes finishes.
Ready: you buy the finished product as it is.
7. Which suits your profile?
| Investor profile | Best option | Why |
|---|---|---|
| Long-term growth and higher ROI | Off-plan | Lower entry price, flexible payments and appreciation potential |
| Immediate cash flow and low risk | Ready | Instant rental income, a tangible asset and less uncertainty |
| Balanced, moderate risk | Both | Diversify between immediate income and long-term gains |
Worked example: AED 2 million, off-plan vs ready
| Off-plan (60/40 plan) | Ready property (cash) | |
|---|---|---|
| Paid upfront | About 10% booking plus the 4% DLD fee | 100% of the price plus the 4% DLD fee and costs |
| During construction | Instalments up to 60% in total | Not applicable |
| At handover | The remaining 40%, often with a mortgage | Already paid |
| Rental income | Starts after handover | Starts almost immediately |
| Price growth | Potential gain during construction | Steady, market-driven |
An illustration only. Payment plans vary by developer and project.
Checklist before you buy off-plan
- Check the developer's delivery record on past projects.
- Confirm the project is registered and payments go into its escrow account.
- Read the SPA's handover date, delay clauses and resale rules.
- Plan how you'll fund the payment due at handover.
- Compare the expected service charges with similar ready buildings.
Checklist before you buy ready
- View the property and check its condition, or use a snagging inspector.
- Compare the price with recent sales in the same building.
- Check the current tenancy, if it's rented, and the building's rental rules.
- Confirm the service charges and any outstanding dues before transfer.
Final thoughts
Off-plan property stands out for investors focused on capital growth, lower entry prices and flexible payments, but it carries more risk and delays income. Ready property suits investors who want stability and returns from day one. Many of my clients hold both.
Want to see the process in detail? Read how buying off-plan in Dubai works, or learn how to resell off-plan before handover.
Frequently asked questions
Is off-plan property cheaper than ready property in Dubai?
Usually, yes. Off-plan property is typically 10% to 30% cheaper than comparable ready property, and it's paid in instalments during construction.
What rental yield does ready property earn in Dubai?
Typical gross yields range from about 5% to 9%, depending on the location and type of property.
Can I sell off-plan property before handover?
Usually, yes, once you've paid the developer's minimum share of the price and received their NOC. See the guide to reselling off-plan before handover.
Can I get a mortgage for off-plan property?
Most banks finance off-plan property at handover rather than during construction, so buyers usually pay the construction instalments in cash.
RERA-licensed real estate consultant at Aeon & Trisl, specialising in off-plan and investment property, with AED 600M+ in closed deals and 100+ clients worldwide.